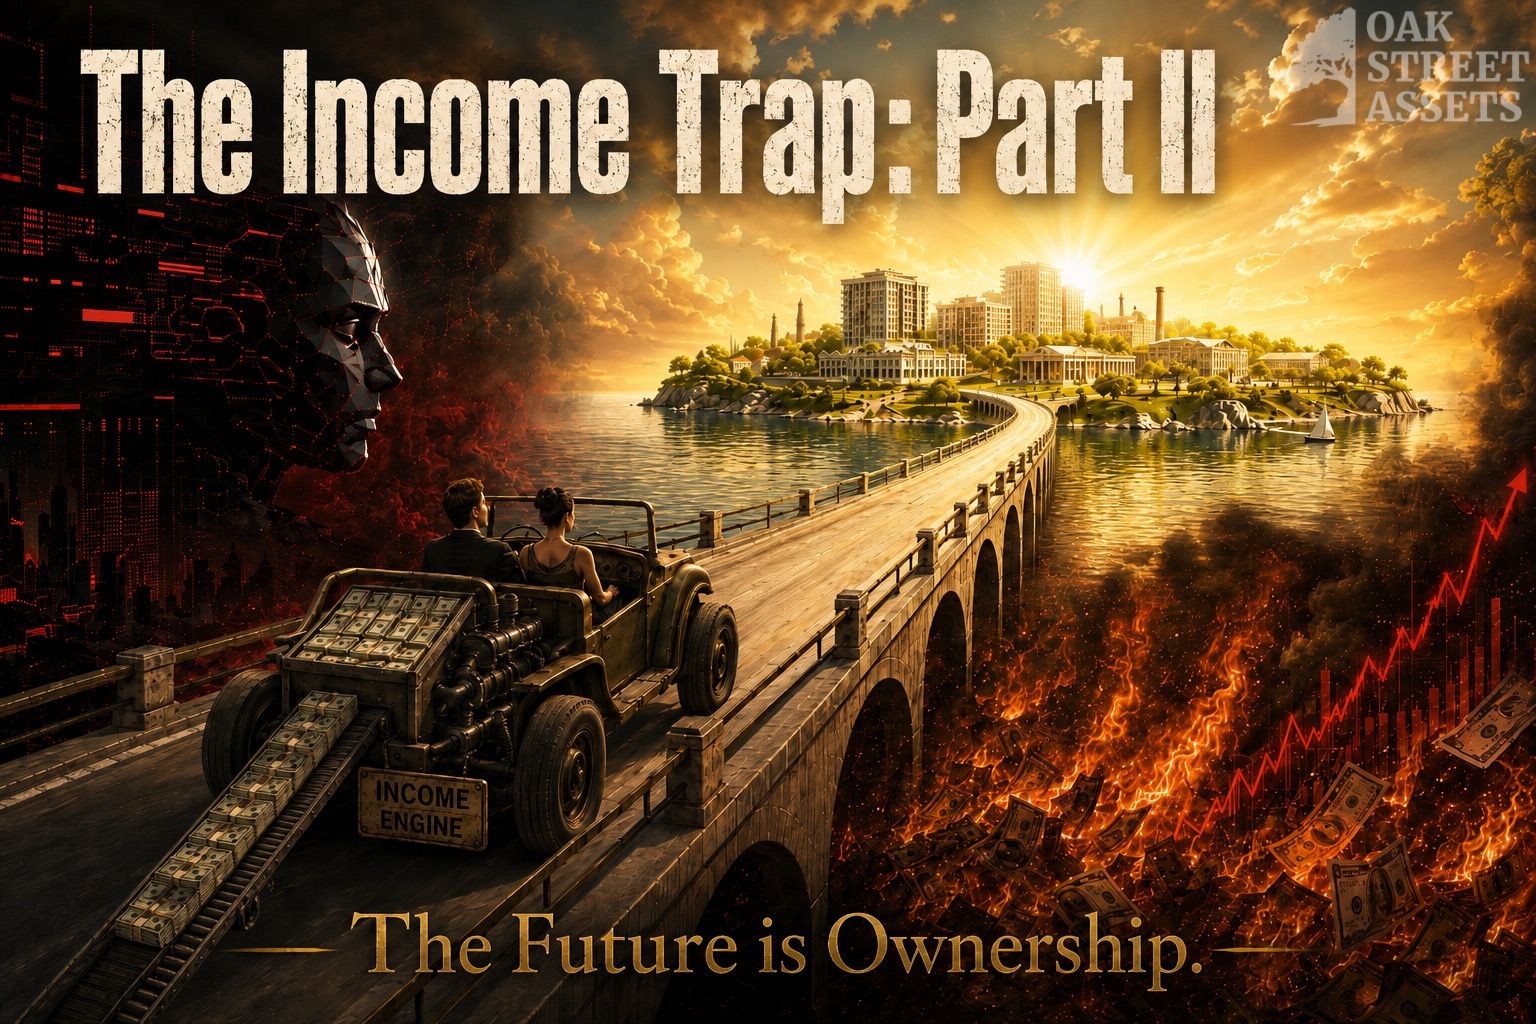

There are two economies operating in America today.
The Income Economy and the Asset Economy.
Most people spend their entire lives in the first. A smaller group quietly benefits from the second.
The first group trades time for money. The second owns things that generate money.
Here’s a simple question:
If your income stopped tomorrow, how long would your lifestyle continue?
For many people, the answer is measured in months. For asset owners, it may be measured in years — or indefinitely.
The first group worries about raises, layoffs, taxes, and inflation. The second focuses on cash flow, appreciation, leverage, and ownership.
Over time, the gap between these two groups becomes enormous. And it has very little to do with how much income they earn. It has everything to do with what they own.
Income can build a lifestyle. Assets can build a future.
The Two Economies
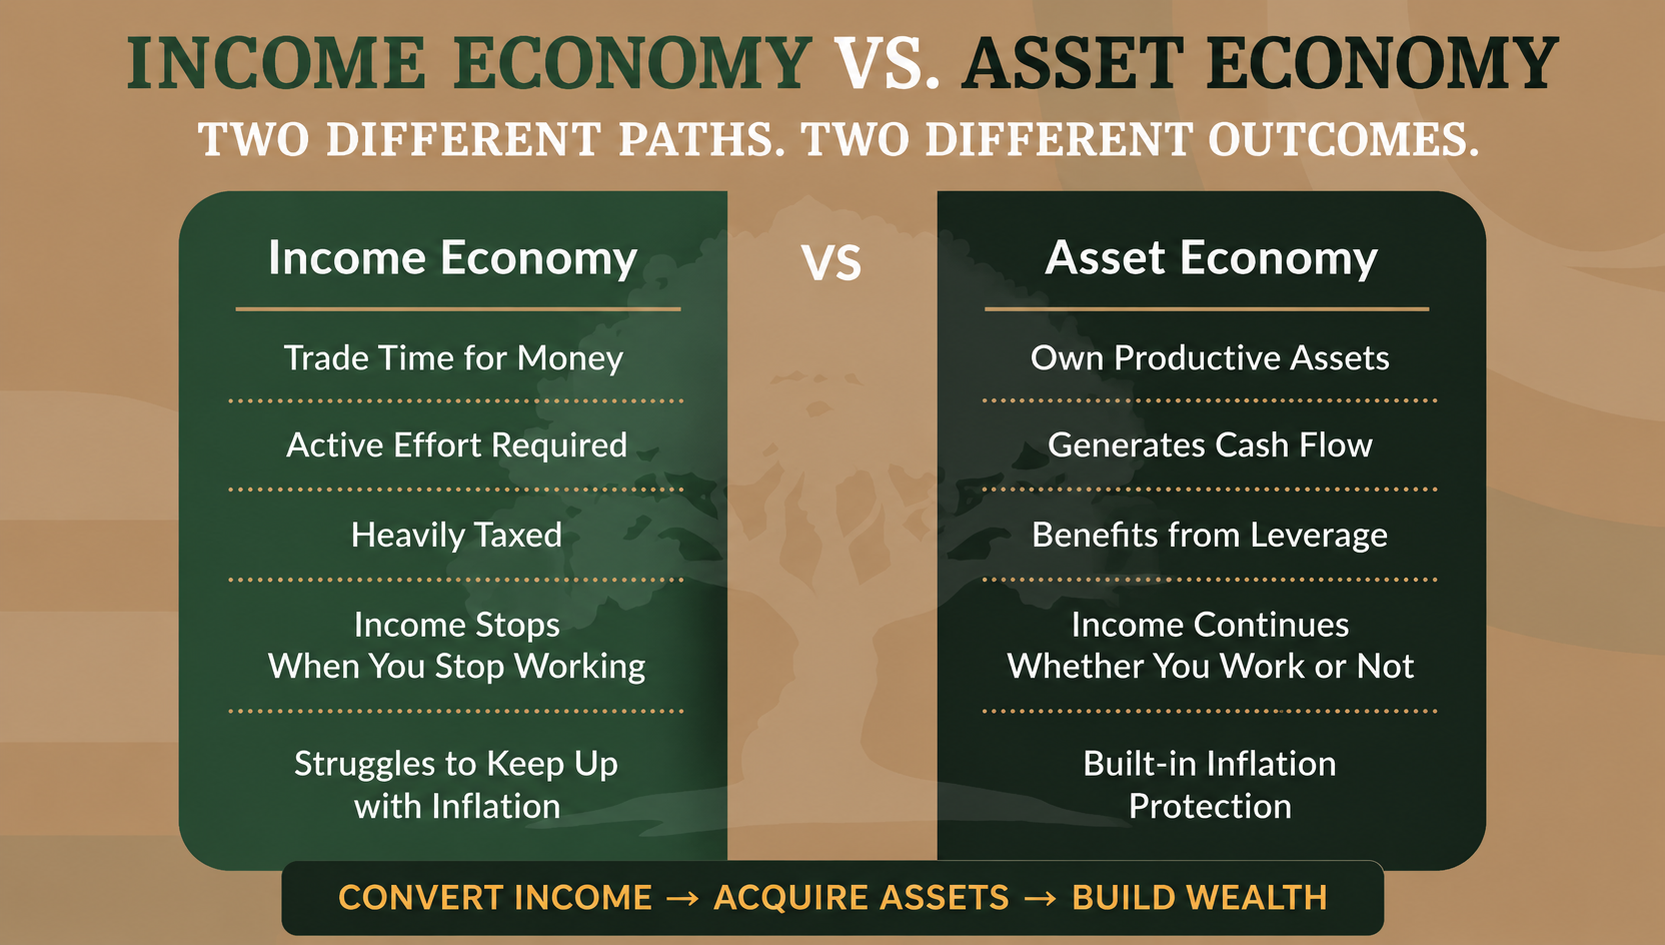
Most people are taught that financial success comes from earning more money. Get an education. Develop valuable skills. Work hard. Build a successful career. Earn a larger income.
There is certainly truth in that advice. Income is often the starting point of wealth creation.
But income alone rarely creates financial freedom.
That is because there is a fundamental difference between earning money and owning assets.
In the Income Economy, people are rewarded primarily for what they do. In the Asset Economy, people are rewarded primarily for what they own.
One depends on continued effort. The other benefits from ownership, leverage, and compounding.
Understanding that distinction may be one of the most important financial lessons of our time.
Ownership Is Becoming the New Divide
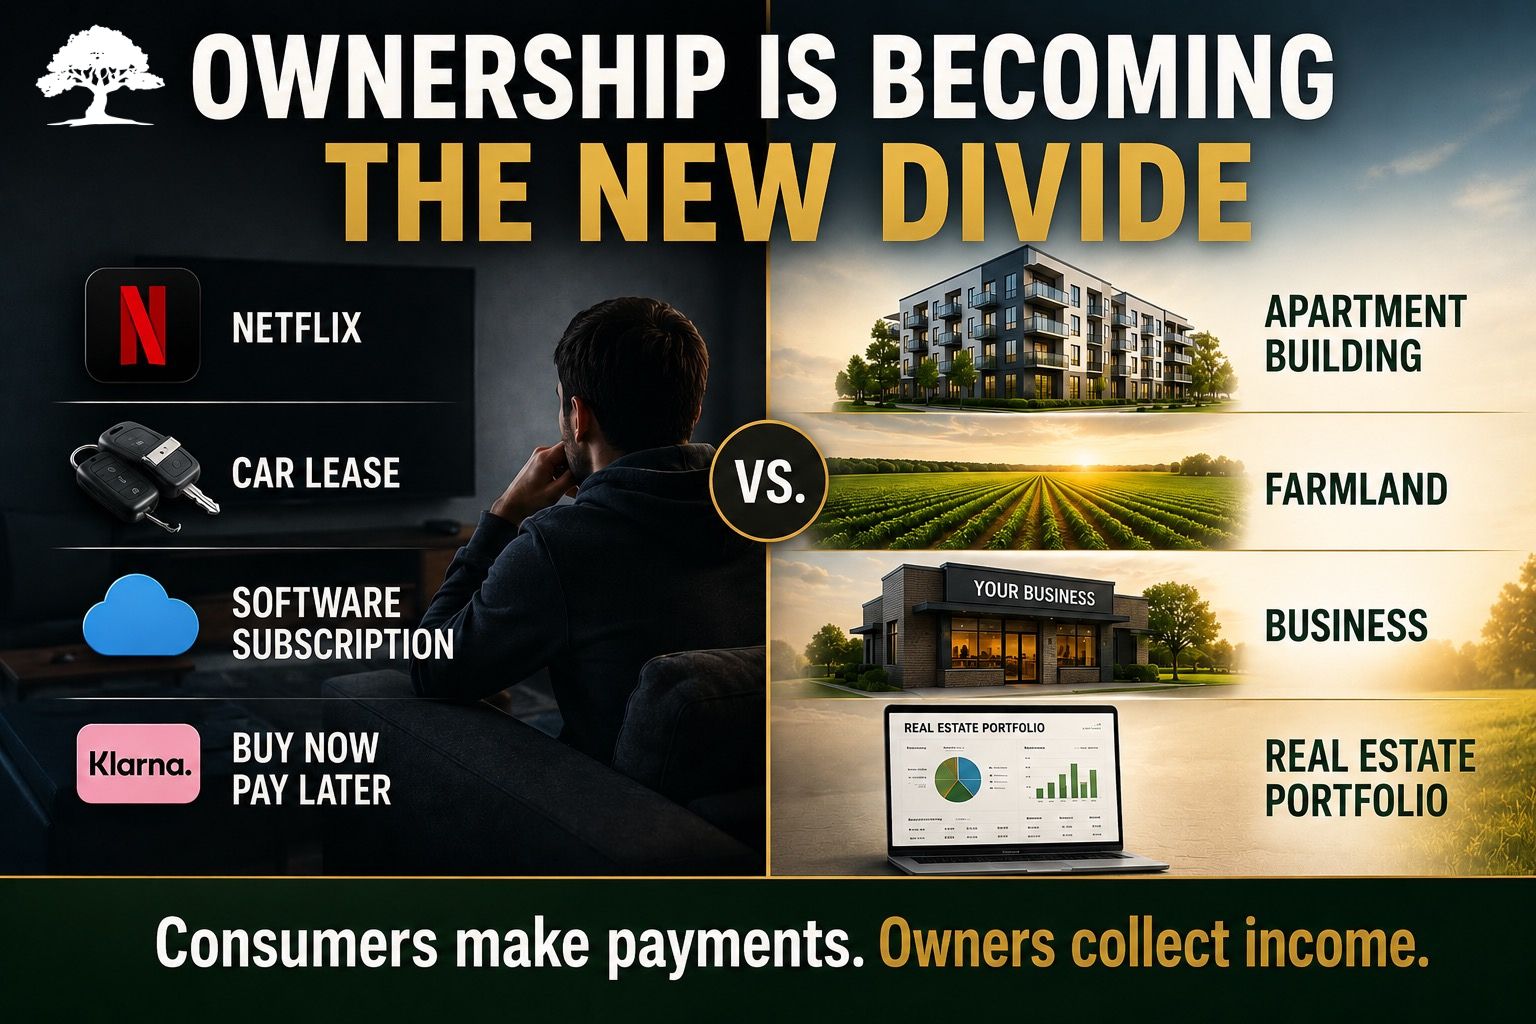
A growing number of people are financing everything. Subscriptions replace ownership. Payments replace savings. Consumption replaces investing.
People rent movies, music, software, cars, equipment, storage, and increasingly even parts of their lifestyle. Ownership is becoming optional — and that’s exactly how many businesses want it.
Subscriptions, financing, and “Buy Now, Pay Later” programs have made consumption easier than ever. But while consumers make monthly payments, asset owners collect them.
Meanwhile, institutions continue acquiring productive assets — apartment communities, industrial properties, farmland, infrastructure, energy assets.
The divide is increasingly becoming less about income and more about ownership. Those who own productive assets participate in economic growth. Those who do not often spend their lives paying for access to assets owned by someone else.
If inflation averages just 2–4% annually over the next thirty years, the question is not whether assets will appreciate. The question is whether you will own them.
Why High Earners Often Fall Behind
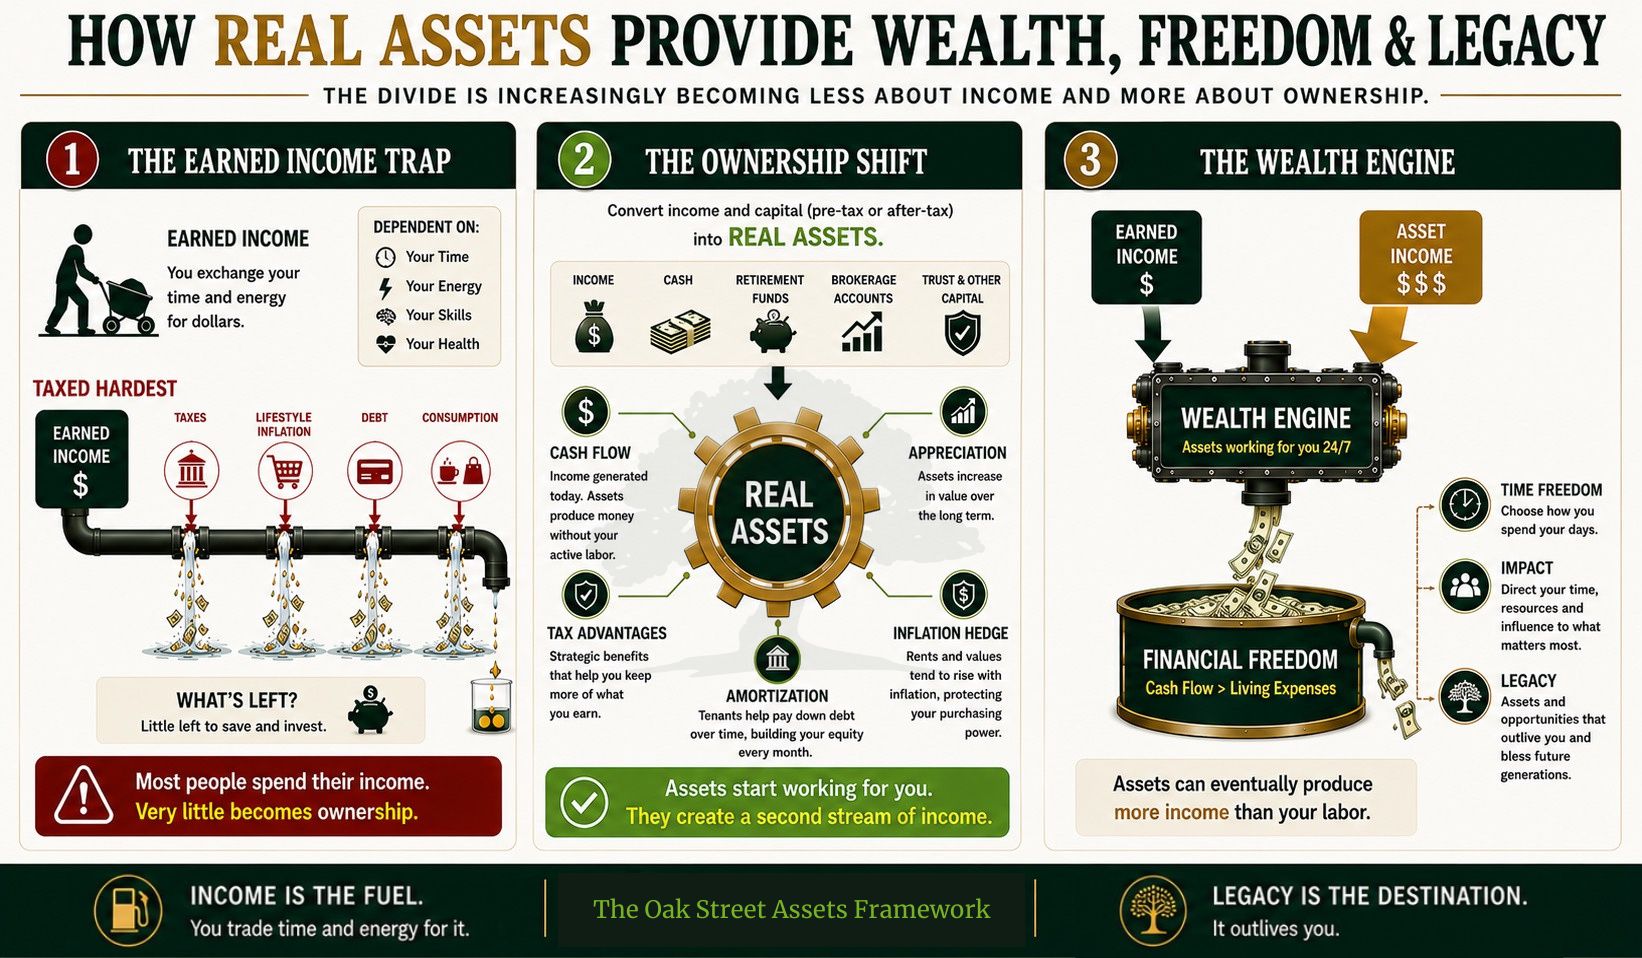
Many people assume financial success is simply a function of income. If that were true, every physician, attorney, executive, entrepreneur, and business owner would eventually become financially independent. Yet we know that isn’t the case.
The real issue is that many high earners become trapped in a cycle that looks like this:
- Earn more.
- Spend more.
- Upgrade lifestyle.
- Pay more taxes.
- Repeat.
The income grows, but the assets never do. As a result, the individual becomes dependent on maintaining a high level of earned income indefinitely.
This is the Income Trap. The trap isn’t a lack of income. It’s a lack of ownership. Income is the fuel. Assets are the destination.
Want to learn how investors use real estate to generate cash flow, reduce taxes, and build long-term wealth?
→ Explore our investment strategy
→ Join our Investor Club and get notified of new opportunities
Inflation: The Silent Wealth Killer
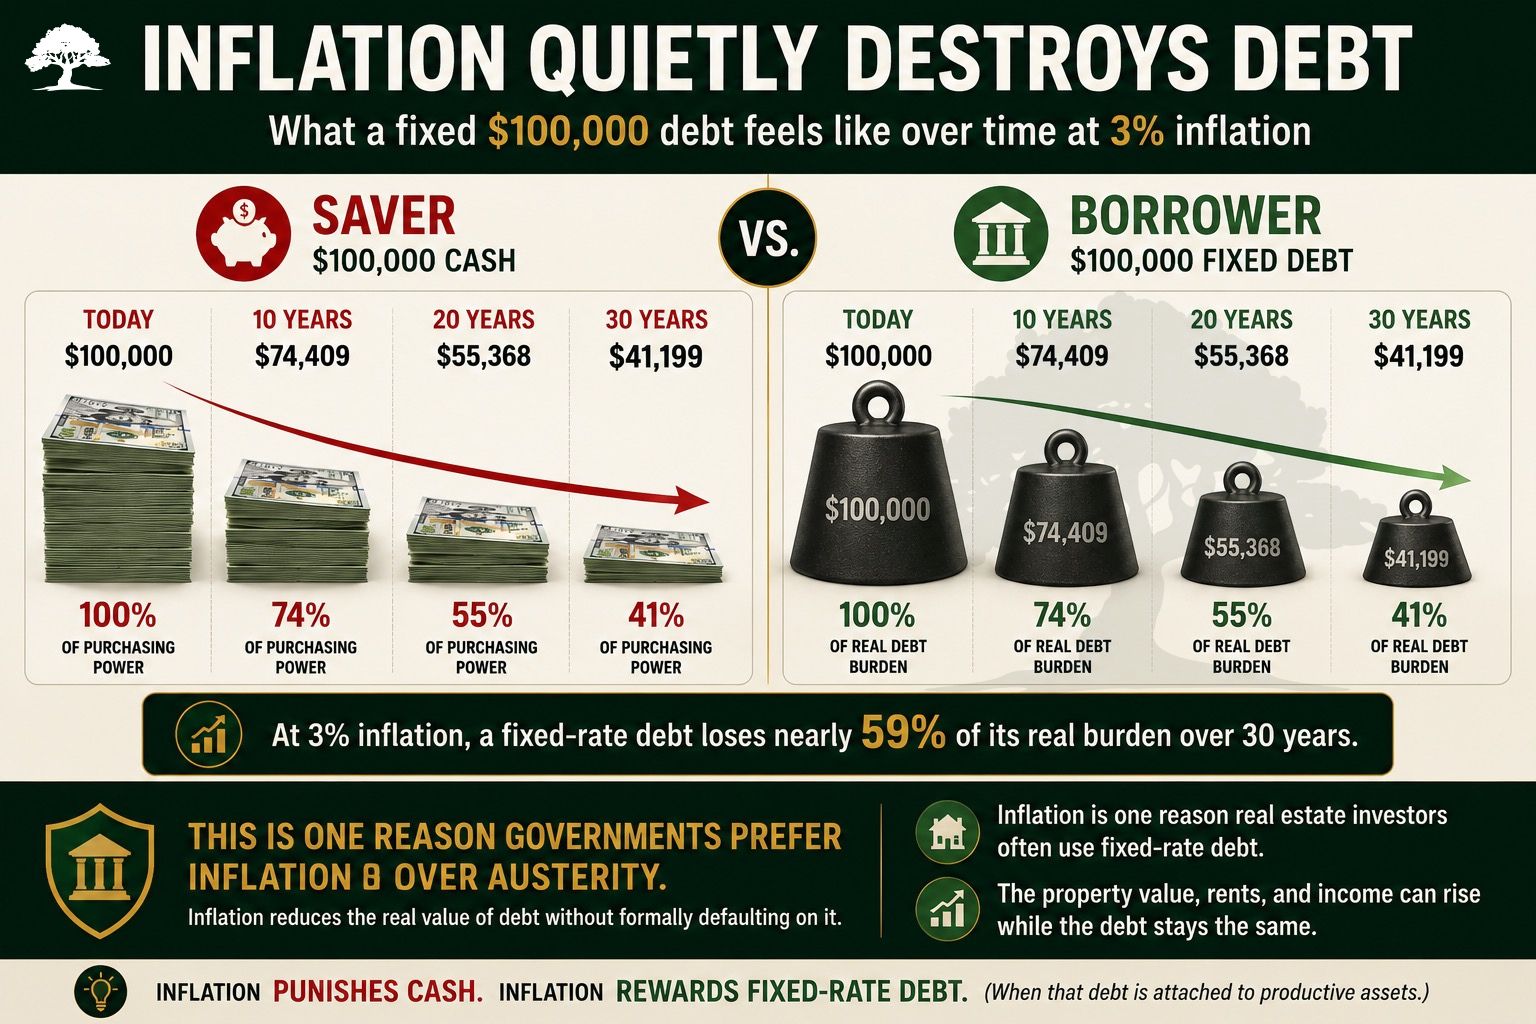
Most people think inflation simply means higher prices. But inflation is much more significant than that.
Inflation quietly reduces the purchasing power of every dollar you save. A dollar today buys less than a dollar did ten years ago. And if inflation averages only 3% annually, purchasing power is cut nearly in half over twenty-five years.
This creates a major challenge for wage earners. Even when salaries increase, many households find themselves running harder simply to maintain their standard of living.
Asset owners experience inflation differently. Apartment rents rise. Land values adjust. Replacement costs increase. Businesses raise prices. Productive assets often have the ability to reprice alongside inflation. Rather than being harmed by inflation, asset owners frequently participate in it.
The Government’s Incentive
This is not a political issue. It doesn’t matter which party is in office.
The reality is that governments carrying large debt burdens have historically benefited from moderate inflation. Why? Because inflation reduces the real value of existing debt. The debt remains the same on paper, but the dollars used to repay it become worth less over time.
In other words, inflation becomes one of the few politically acceptable ways to reduce the burden of enormous debt obligations. Whether intentional or not, the long-term result is often the same:
Cash becomes less valuable. Productive assets become more valuable. Understanding this dynamic may be one of the most important financial lessons of the coming decades.
What Is a Real Asset?
Not everything that increases in price is an asset. A true asset generally does one or more of the following:
- Produces income
- Solves a problem
- Provides utility
- Creates economic value
- Benefits from growing demand
A productive apartment community is a good example. People need housing. The property generates rental income. Value can be created through operations and improvements. Appreciation becomes a byproduct of delivering value.
That is fundamentally different from buying something and simply hoping someone else pays more for it later. Real wealth is often built through productive assets first and appreciation second.
Why Real Estate Has Created More Millionaires Than Almost Any Other Asset Class
Real estate combines several wealth-building advantages that are rarely found together.
Cash Flow
Income-producing real estate can generate recurring cash flow — income that arrives whether or not you show up to work.
Appreciation
Well-located properties tend to increase in value over time as population, wages, and replacement costs rise.
Leverage
Investors can control large assets using borrowed capital. This allows appreciation to occur on the full asset value, not just the equity invested.
Inflation Protection
As prices rise, rents often rise as well. Meanwhile, fixed-rate debt remains unchanged. Inflation can actually improve the economics of long-term fixed-rate borrowing by reducing the future purchasing power of the dollars used to repay it.
Imagine buying a $1 million property with a fixed-rate loan today and repaying that debt over the next thirty years with future dollars that are worth significantly less than today’s dollars. Inflation works against savers, but it can work in favor of leveraged asset owners.
Tax Advantages
Real estate offers unique tax benefits that are difficult to replicate elsewhere, including:
- Depreciation
- Cost segregation
- Bonus depreciation
- 1031 exchanges
- Passive income strategies
For many investors, after-tax returns become just as important as pre-tax returns.
The Wealth Formula Hasn’t Changed
Despite changing technology, changing politics, and changing markets, the formula for building wealth remains remarkably simple:
Earn income. Spend less than you earn. Consistently acquire productive assets. Allow time and compounding to work. Repeat.
The goal is not to stop working. The goal is to create options — to reach a point where your assets generate enough income that work becomes a choice rather than a necessity.
Final Thoughts
The wealthiest people in the world do not primarily live on earned income. They live on the cash flow, appreciation, and growth generated by assets they own.
The path to financial freedom is not necessarily earning more. The path is converting earned income into productive assets as efficiently and consistently as possible.
For decades, most people have focused almost exclusively on increasing their income. The next decade may belong to those who focus on increasing their ownership.
At Oak Street Assets, we help investors make that transition. Because income can create a good living. But assets create lasting wealth.
Own Assets. Own Your Time.
What’s Next?
This article focused on a timeless principle: convert income into productive assets. But a growing question remains: what happens when technology begins competing with knowledge workers, professionals, and even highly paid specialists?
Artificial intelligence is changing the economics of labor, while inflation continues to erode the purchasing power of wages and savings. In our next article, we’ll explore why asset ownership may become even more important in an era of AI, automation, and currency devaluation.
Now Live: AI Is Coming for Jobs. Inflation Is Coming for Dollars. Who Wins?
In the meantime, you can explore more investing insights and market commentary on the Oak Street Assets blog.
Curious how Oak Street Assets helps investors convert income into cash-flowing real estate assets?
Schedule a conversation here.